
Prime Minister Apna Ghar Scheme 2026 Guide
Quick answer: The Prime Minister Apna Ghar Scheme 2026, officially named the Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna, is a government-backed affordable housing finance programme. Current official information provides financing of up to Rs10 million, up to 20 years, with 5% fixed pricing for the first 10 years, subject to the programme’s eligibility and financing conditions.
Prime Minister Apna Ghar Scheme 2026: Key Facts
| Fact | Verified information |
|---|---|
| Official current name | Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna |
| Previous name | Mera Ghar-Mera Ashiana |
| Maximum financing | Up to Rs10 million |
| Customer pricing | 5% for first 10 years |
| Period beyond 10 years | Applicable market/bank pricing |
| Maximum tenure | Up to 20 years |
| Housing unit | House up to 10 Marla / 2,720 sq. ft. |
| Apartment | Up to 1,500 sq. ft. |
| Financing structure | 90% financing / 10% borrower equity |
| Eligible use | House/flat purchase, construction on owned plot, or plot purchase with construction |
| Processing fee | No processing cost |
| Prepayment penalty | No prepayment penalty |
| General eligibility | First-time homeowners with valid CNIC who do not own a housing unit |
| Current programme portal | apnaghar.gov.pk |
| Current official status | Active programme information available in 2026 |
The scheme was previously called Mera Ghar-Mera Ashiana. The Ministry of Housing and Works formally renamed it Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna through its March 26, 2026 notification, communicated by SBP on April 1, 2026.
What is the Prime Minister Apna Ghar Scheme 2026?
The Prime Minister Apna Ghar Scheme, officially titled the Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna, is a Government of Pakistan affordable housing finance initiative.
The programme is designed to make housing finance more accessible to eligible first-time homeowners. Financing can be used for purchasing a house or flat, constructing a house on an already owned plot, or purchasing a plot and constructing a house.
The programme is implemented through participating financial institutions, with the State Bank of Pakistan involved in the scheme’s implementation framework. The official programme portal provides an online application facility and information about participating institutions.
Why do some websites call it Mera Ghar-Mera Ashiana?
This is because the programme was originally introduced under the name Mera Ghar-Mera Ashiana.
The Ministry of Housing and Works notified on March 26, 2026 that the scheme would henceforth be called:
Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna.
SBP subsequently directed participating financial institutions to use the revised name in official correspondence and related documents.
This distinction matters when researching the programme because older pages may still use the former name.
Who is eligible?
The official programme portal identifies the general eligibility category as:
- First-time homebuyers
- Pakistani citizens holding a valid CNIC
- Applicants who do not own a housing unit in their name
Meeting these conditions does not by itself guarantee financing. The relevant financial institution will still apply its financing, verification and documentation requirements.
Overseas Pakistanis
The eligibility framework was expanded in June 2026.
SBP’s June 15, 2026 circular says that Overseas Pakistanis/Non-Resident Pakistanis holding NICOP/POC may also obtain financing under the Wazir-e-Azam Apna Ghar Program.
Because individual bank products can have additional conditions, an NRP applicant should confirm the applicable process with the participating institution before submitting an application.
A recent eligibility clarification
SBP also clarified on September 14, 2026 that employees of banks, DFIs and MFBs themselves are not eligible to obtain financing under the programme.
This is a specific exclusion and should not be interpreted as a general exclusion of people working in other sectors.
What can the financing be used for?
Current official programme information identifies three main purposes:
- Purchase of a house or flat
- Construction of a house on an already owned plot
- Purchase of a plot and construction of a house
The official programme portal and participating-bank information both identify these uses.
Before buying a particular property, applicants should confirm that its legal status, documentation and other bank requirements satisfy the participating institution’s requirements.
Loan amount, markup and tenure
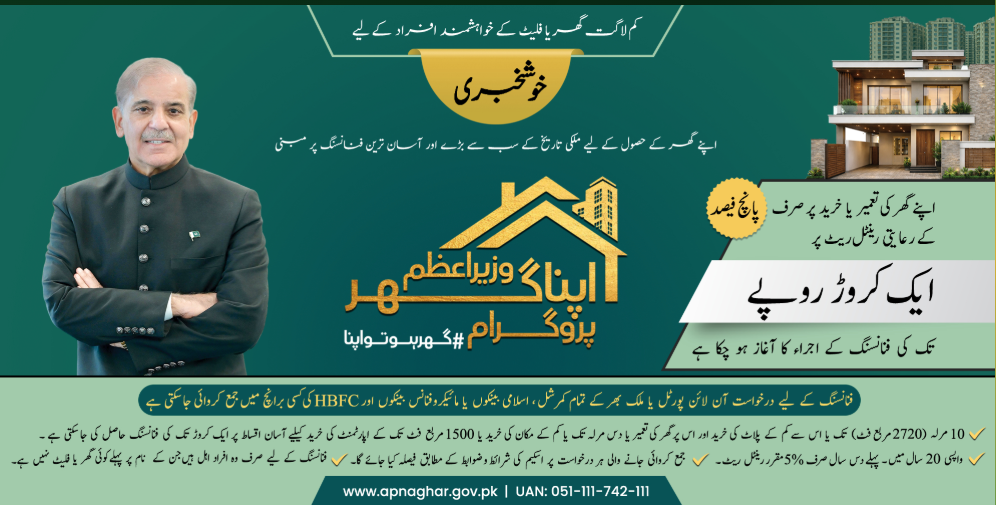
The current programme provides financing of up to Rs10 million.
The maximum repayment period is 20 years. The customer/end-user pricing is 5% for the first 10 years. For financing extending beyond 10 years, the applicable bank/market pricing applies rather than the initial 5% rate continuing for the full 20 years.
This distinction is important when estimating installments.
Is the rate 5% for all 20 years?
No.
For the current programme structure, the subsidized customer pricing is 5% for the first 10 years. If the loan continues beyond that period, the applicable pricing for the remaining period must be taken into account. Participating-bank information describes this as the applicable bank pricing, with the scheme’s bank pricing referenced to one-year KIBOR plus 3%.
Therefore, a calculator should not present a 20-year installment calculated permanently at 5% as the actual expected repayment schedule.
Property size and 90:10 financing
The current programme covers:
- A house up to 10 Marla / 2,720 sq. ft.
- A flat/apartment up to 1,500 sq. ft.
The maximum financing is Rs10 million.
The financing structure is 90:10, meaning the financing can cover up to 90% while the borrower contributes the remaining 10% equity, subject to the programme and bank’s applicable conditions.
Example of 90:10 financing
Suppose an eligible property costs Rs8 million and the financing structure applicable to the transaction is 90:10.
- 90% financing = Rs7.2 million
- 10% borrower contribution = Rs800,000
The example is mathematical only. Actual financing depends on the bank’s assessment, property valuation and applicable programme conditions.
Participating Banks and Financial Institutions
The official Apna Ghar portal currently lists a network of participating financial institutions, including commercial banks, Islamic banks, microfinance banks and the House Building Finance Company.
The portal currently describes the network as 31+ participating financial institutions and provides the current institution list.
Because the participating-institution list can change, readers should check the current official list rather than relying on an old blog post or social-media list.
Official participating-institution list: Wazir-e-Azam Apna Ghar official portal
How to Apply
The official portal currently provides an online application route.
Step 1: Check eligibility
Confirm that you fall within the programme’s current eligibility requirements and that the intended property/use fits the programme.
Step 2: Create an account
The official portal instructs new applicants to create an account before applying.
The registration form requires information including:
- CNIC
- Full name
- Mobile number
- Email address
- Password
Step 3: Log in
After registration, log in to the Apna Ghar portal.
Step 4: Complete the loan application
Fill in the requested information and provide the required documentation.
Step 5: Submit the application
The official portal instructs applicants to submit the completed loan application through the platform.
Step 6: Verification and processing
The relevant participating financial institution will process the application and perform its required verification.
Approval should not be treated as automatic simply because an applicant meets the general programme description.
Required Documents
The exact document checklist can vary according to the applicant’s employment/income profile and the participating institution.
For example, participating-bank application material can distinguish between salaried, formal-business and informal-income applicants.
A practical document checklist should therefore be treated as:
- Valid CNIC/NICOP/POC where applicable
- Income evidence applicable to the applicant
- Employment/business evidence where required
- Bank statements where required
- Property/title documents where applicable
- Other documents requested by the participating financial institution
[VERIFY: exact current programme-wide document checklist from official programme documentation]
Do not assume that a document required by one bank is automatically required by every participating institution.
Apna Ghar Installment Examples
The examples below use the standard reducing-balance monthly-payment formula:
M = P × r × (1+r)ⁿ / ((1+r)ⁿ − 1)
Where:
- P = loan principal
- r = monthly rate
- n = number of monthly payments
- Annual rate = 5%
- Monthly rate = 5% ÷ 12
- Repayment frequency = monthly
- Tenure = 10 years
- Number of payments = 120
These examples deliberately use a 10-year tenure, because the entire illustrated repayment period falls within the verified 5% pricing period.
They are estimates, not bank quotations, and exclude any charges or costs that may apply outside the stated financing assumptions.
Example 1: Rs2.5 million
| Item | Example |
|---|---|
| Loan amount | Rs2,500,000 |
| Annual rate | 5% |
| Tenure | 10 years |
| Payments | 120 monthly payments |
| Estimated monthly installment | Rs26,516 |
| Estimated total repayment | Rs3,181,965 |
| Estimated total markup | Rs681,965 |
Example 2: Rs5 million
| Item | Example |
|---|---|
| Loan amount | Rs5,000,000 |
| Annual rate | 5% |
| Tenure | 10 years |
| Payments | 120 monthly payments |
| Estimated monthly installment | Rs53,033 |
| Estimated total repayment | Rs6,363,931 |
| Estimated total markup | Rs1,363,931 |
Example 3: Rs10 million
| Item | Example |
|---|---|
| Loan amount | Rs10,000,000 |
| Annual rate | 5% |
| Tenure | 10 years |
| Payments | 120 monthly payments |
| Estimated monthly installment | Rs106,066 |
| Estimated total repayment | Rs12,727,862 |
| Estimated total markup | Rs2,727,862 |
What about a 20-year loan?
A 20-year loan cannot be accurately represented by simply applying 5% to the full 20 years because the programme’s 5% customer pricing applies to the first 10 years.
For a 20-year calculation, the first 10 years can be estimated using the verified 5% rate. The remaining 10 years require the applicable pricing at that stage.
[VERIFY: rate and precise repricing mechanism applicable to the reader’s remaining tenure at the time of calculation]
Advantages and Limitations
Potential features of the programme
- Financing can reach Rs10 million.
- The maximum tenure is 20 years.
- Customer pricing is fixed at 5% for the first 10 years.
- Financing can cover purchasing or constructing qualifying housing.
- The programme uses a 90:10 financing/equity structure.
- Official programme information states there is no processing cost and no prepayment penalty.
Important limitations
- The programme is intended for eligible first-time homeowners and has ownership conditions.
- Property size limits apply.
- The maximum financing is Rs10 million.
- A 20-year loan does not remain at the initial 5% customer pricing for the entire period.
- Approval is subject to the relevant financial institution’s verification and conditions.
- Property documentation and valuation can affect the financing process.
- Other actual transaction costs may still apply even where the programme states there is no processing cost.
Common Application Problems
Applicants should take care to avoid straightforward procedural issues such as:
- Providing incorrect personal information
- Submitting incomplete information
- Failing to provide requested documents
- Applying for a property that does not meet programme requirements
- Assuming general eligibility guarantees loan approval
- Using outdated programme information
- Relying on an unofficial application channel
Property documentation is particularly important in housing finance. Requirements can vary depending on the relevant land-record authority and financing institution. SBP notes that property-document requirements can vary between land-record authorities and other relevant authorities.
Scam Warning
Be careful with anyone claiming that they can provide:
- Guaranteed approval
- Guaranteed government financing
- Faster approval in exchange for an unofficial payment
- Access to a special quota
- An unofficial application link
Use the official programme portal and verify bank information directly with the participating financial institution.
The official programme portal is:
The official portal currently provides an application route and programme information.
Do not send CNIC information, banking information or money to an unofficial website merely because it uses the words “Apna Ghar,” “Prime Minister,” or “government scheme.”
What to Do Next
If you are considering the programme:
- Check the current eligibility rules.
- Confirm that your intended property/use falls within the programme.
- Estimate the financing amount and your 10% equity contribution.
- Calculate an estimated installment.
- Prepare your income and property documents.
- Check the current participating-institution list.
- Apply through the official programme channel or participating institution.
- Verify all current terms before paying any fee or signing financing documents.
Apna Ghar Calculator
A SmartCalculator housing calculator can help you estimate the payment associated with a particular loan amount and repayment period.
Inputs to enter
Typically, you would enter:
- Loan amount
- Annual markup/rate
- Loan tenure
- Payment frequency
What the calculator estimates
A reducing-balance loan calculator can estimate:
- Monthly installment
- Total repayment
- Total markup/interest
- Repayment schedule, where supported
For the Apna Ghar programme, the important assumption is the 5% rate during the first 10 years.
A simple calculator should not present a 20-year loan as though 5% necessarily applies for all 20 years. For a loan extending beyond 10 years, the future applicable rate must be incorporated into the calculation.
Calculator page: [VERIFY: SmartCalculator Apna Ghar/home-finance calculator URL]
Comparison: Apna Ghar Financing vs a Standard Housing Loan
The following is a structural comparison rather than a ranking.
| Feature | Wazir-e-Azam Apna Ghar Program | Standard housing finance |
|---|---|---|
| Programme pricing | 5% customer pricing for first 10 years | Depends on lender/product |
| Maximum financing | Up to Rs10 million under programme | Depends on lender/product |
| Maximum tenure | Up to 20 years | Depends on lender/product |
| Housing size | Programme limits apply | Depends on lender/product |
| First-time ownership condition | Applies | Depends on product |
| Financing uses | Purchase/construction/plot+construction as permitted | Depends on product |
| Equity structure | 90:10 | Depends on lender/product |
| Processing cost | No processing cost under programme information | Depends on lender |
| Prepayment penalty | No prepayment penalty under programme information | Depends on lender/product |
| Pricing after 10 years | Applicable bank/market pricing | Depends on product |
The relevant terms should always be compared using current written offers from the lender rather than relying on a general description.
Frequently Asked Questions
The current official name is Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. It is a government affordable housing finance programme for eligible applicants, with financing of up to Rs10 million and a maximum tenure of 20 years.
Yes. The official Apna Ghar portal is operating in 2026 and provides programme information and an online application route. The programme was also subject to further SBP implementation updates during 2026.
The current official programme information states that financing can be up to Rs10 million. Actual financing depends on eligibility, property and the relevant financial institution’s assessment
The programme provides 5% customer/end-user pricing for the first 10 years. A loan continuing beyond 10 years is subject to the applicable pricing for the remaining period, so 5% should not automatically be used for the entire 20-year tenure.
Yes. The programme includes construction of a house on an already owned plot. It also includes purchase of a plot followed by construction, subject to the applicable programme and bank conditions.
The current programme information allows a house of up to 10 Marla / 2,720 sq. ft. or an apartment of up to 1,500 sq. ft.
SBP’s June 15, 2026 implementation update states that Overseas Pakistanis/NRPs holding NICOP or POC may obtain financing under the programme. Applicants should confirm the applicable process and conditions with the relevant participating institution.
The official programme portal instructs new applicants to create an account, log in, complete the loan application and submit it. Applicants can also use participating financial institutions according to the programme’s current implementation arrangements.
The current official programme information states that there is no processing cost and no prepayment penalty under the scheme. Other transaction-related costs, where applicable, should still be confirmed with the relevant financial institution.
The current programme is the renamed version of the scheme previously called Mera Ghar-Mera Ashiana. A Ministry of Housing and Works notification dated March 26, 2026 approved the new name, Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna.
Conclusion
The Prime Minister Apna Ghar Scheme 2026, officially known as the Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna, provides eligible applicants with housing finance of up to Rs10 million, a maximum tenure of 20 years and 5% customer pricing for the first 10 years.
The most important points to verify are your eligibility, property size, financing requirement, equity contribution and the pricing that will apply if your loan continues beyond the first 10 years.
Before applying, check the latest official programme information and participating institution list.
For installment planning, use the relevant SmartCalculator housing/loan calculator with the actual loan amount, rate and tenure.